Expense control and monthly budgeting aren’t one-time fixes; they’re ongoing habits that compound over time. In the first few months, budgeting can feel effortful, almost like learning a new language. But as the habit solidifies, it becomes second nature, much like brushing your teeth or checking the weather before heading out.
The people who succeed at long-term financial discipline aren’t the ones with perfect willpower. They’re the ones who build systems that make good decisions easier and bad decisions harder: automated savings, weekly check-ins, realistic limits, and a clear sense of why they’re doing it in the first place. Whether your motivation is financial freedom, a specific goal, or simply peace of mind, anchoring your budget to that purpose makes the discipline far easier to sustain.
Over months and years, small, consistent choices, cutting an unused subscription, waiting 24 hours before an impulse buy, reviewing your budget every Sunday evening, accumulate into significant financial progress. That’s the quiet power of expense control: it rarely feels dramatic in the moment, but it changes everything over time.
Conclusion
Keeping your expenses under control isn’t about restriction or sacrifice; it’s about intention. A monthly budget gives you visibility into your money, a plan for reaching your goals, and a buffer against life’s inevitable surprises. It transforms financial anxiety into financial confidence, one month at a time.
Start small. Track your spending for the next 30 days, build a simple budget using a framework that fits your life, and commit to a short weekly review. You don’t need to get it perfect on the first try, you just need to start. Every month you stick with it, you’ll get a little better, a little more in control, and a lot closer to the financial life you actually want.
FAQS
1.What is the 50/30/20 budgeting rule?
The 50/30/20 rule is a simple budgeting framework where 50% of your after-tax income goes toward needs (rent, groceries, utilities), 30% goes toward wants (entertainment, dining out, hobbies), and 20% goes toward savings and debt repayment. It’s popular because it’s easy to remember and flexible enough to adapt to different income levels.
2.How much of my income should I save every month?
A common benchmark is to save at least 20% of your take-home income, but the right number depends on your goals, debts, and cost of living. If 20% feels unrealistic right now, start with 5-10% and increase it gradually as your income grows or expenses shrink.
3.What’s the difference between a budget and a financial plan?
A budget is a short-term tool that tracks your monthly income and expenses, while a financial plan is a broader, long-term roadmap that includes goals like retirement, education, home ownership, and investments. A budget is one building block within a larger financial plan.
4.How do I start budgeting if I’ve never done it before?
Start by tracking every expense for 30 days without changing your spending habits. Once you see where your money actually goes, categorize expenses into needs, wants, and savings, then set realistic monthly limits for each category based on your income.
5.What are fixed expenses versus variable expenses?
Fixed expenses stay roughly the same every month, such as rent, loan payments, and insurance premiums. Variable expenses change from month to month, like groceries, fuel, entertainment, and dining out. Budgets need to account for both types separately.
6.Why do I still overspend even though I have a budget?
Overspending despite a budget often happens because the budget is unrealistic, categories are too broad, or emotional and impulse spending isn’t accounted for. Reviewing your budget weekly and building in a small discretionary buffer can help close this gap.
7.How often should I review my monthly budget?
Ideally, review your budget weekly for quick check-ins and do a full review at the end of each month. This helps you catch overspending early and adjust before small issues become big financial problems.
8.What’s the best budgeting method for beginners?
The envelope method or the 50/30/20 rule are usually the easiest for beginners because they’re simple to understand and don’t require complex spreadsheets. As you get more comfortable, you can move to zero-based budgeting for tighter control.
9.What is zero-based budgeting?
Zero-based budgeting means every unit of your income is assigned a job, whether it’s spending, saving, or debt repayment, so that income minus expenses equals zero at the end of the month. It forces intentional decisions about every dollar.
10.How can I control impulse spending?
Try the 24-hour rule: wait a full day before making any non-essential purchase. Unsubscribing from promotional emails, removing saved card details from shopping apps, and setting a small discretionary allowance can also reduce impulse buys.
11.Should I use cash or cards to control my expenses?
Cash can make spending feel more real and is useful for categories where you tend to overspend, like dining out or shopping. Cards are more convenient and easier to track digitally, but they can make overspending less noticeable, so choose based on your spending habits.
12.How do I budget with an irregular income?
Base your budget on your lowest expected monthly income, prioritize essential expenses first, and treat any income above that baseline as a bonus that goes toward savings or irregular expenses. Building a buffer fund is especially important with variable income.
13.What percentage of income should go toward rent or housing?
A common guideline is to keep housing costs at or below 30% of your gross monthly income. In high-cost cities this isn’t always possible, so aim to keep it as low as your circumstances allow while balancing other financial goals.
14.How do I stop living paycheck to paycheck?
Start by tracking all expenses, cutting non-essential spending, building a small emergency fund of even one month’s expenses, and gradually increasing that cushion. Consistency over time matters more than dramatic one-time cuts.
15.What is an emergency fund and how big should it be?
An emergency fund is money set aside specifically for unexpected expenses like medical bills, car repairs, or job loss. Most financial experts recommend saving three to six months’ worth of essential living expenses.
16.How do I budget for irregular or annual expenses?
Break annual or irregular expenses, like insurance premiums or festival spending, into monthly amounts and set that money aside in a separate savings category each month so it doesn’t disrupt your budget when the bill arrives.
17.Are budgeting apps worth using?
Budgeting apps can save time by automatically tracking transactions and categorizing spending, which is especially useful for people who find manual tracking tedious. However, they work best when you actually review the insights they provide, not just link your accounts and forget them.
18.How do I budget as a couple or family?
Start with a joint conversation about financial goals and priorities, then decide whether to combine accounts, keep them separate, or use a hybrid approach. Set a shared budget for household expenses and agree on a process for discussing larger purchases.
19.What’s the biggest mistake people make with budgeting?
The most common mistake is creating an unrealistic budget that’s too restrictive, which leads to frustration and abandoning the budget altogether. A sustainable budget should allow some room for enjoyment, not just strict saving.
20.How can I reduce my monthly grocery expenses?
Plan meals in advance, make a shopping list and stick to it, buy in bulk for non-perishables, compare prices across stores, and avoid shopping while hungry, which tends to increase impulse purchases.
21.Should I pay off debt or save money first?
In most cases, prioritize paying off high-interest debt first since the interest cost usually outweighs typical savings returns, while still contributing a small amount to an emergency fund so unexpected expenses don’t force you back into debt.
22.How do subscriptions affect my monthly budget?
Subscriptions can quietly drain your budget because they’re small recurring charges that are easy to forget about. Reviewing your bank statement every few months to cancel unused subscriptions is one of the simplest ways to free up cash.
23.What is lifestyle inflation and how do I avoid it?
Lifestyle inflation happens when your spending increases in line with your income, leaving little room for extra savings even as you earn more. Avoid it by automatically directing a portion of every raise or bonus straight into savings before you adjust your spending habits.
24.How can I track my expenses without a fancy app?
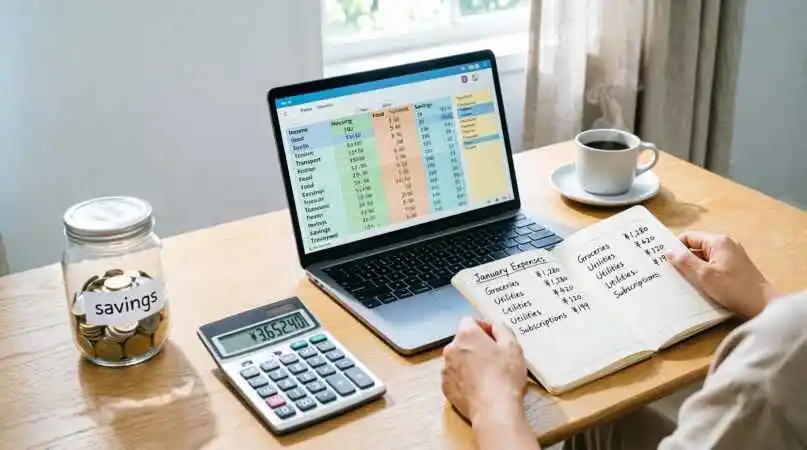
A simple notebook, spreadsheet, or even the notes app on your phone can work well for tracking expenses. What matters most is consistency in logging every expense, not the sophistication of the tool.
25.What’s a good way to cut down on dining-out expenses?
Set a specific monthly limit for eating out, plan a few home-cooked meals in advance, and reserve restaurant visits for special occasions or social plans rather than convenience, which tends to add up quickly.
26.How do I budget for a variable work schedule with tips or commissions?
Calculate your average income over the past six to twelve months and budget based on the lower end of that range, then treat higher-earning months as an opportunity to boost savings rather than increase regular spending.
27.Can budgeting help me get out of debt faster?
Yes, a budget shows exactly how much extra money you can direct toward debt repayment each month, and following methods like the debt snowball or debt avalanche within that budget can help you pay off balances faster and with more consistency.
28.How do I stay motivated to stick to a budget?
Set specific, meaningful goals like a vacation, a home down payment, or debt freedom, track your progress visually, and celebrate small milestones along the way. Motivation tends to fade without a clear reason behind the discipline.
29.What should I do if I go over budget one month?
Review what caused the overspending, adjust the following month’s budget if needed, and avoid the temptation to abandon budgeting altogether. One difficult month doesn’t undo the value of budgeting over the long run.
30.How does controlling expenses affect long-term financial goals?
Controlling expenses directly increases the amount of money available for savings, investments, and debt repayment, which accelerates progress toward long-term goals like buying a home, retiring comfortably, or achieving financial independence.
Disclaimer: The content on this blog is for informational purposes only.The author’s opinions are personal and not endorsed. Efforts are made to provide accurate information, but completeness, accuracy, or reliability are not guaranteed. The author is not liable for any loss or damage resulting from the use of this blog. It is recommended to use the information on this blog at your own discretion.