How to Keep Expenses Under Control: The Complete Guide to Monthly Budgeting
Introduction
Every month feels a little different, but for most people, one thing stays painfully familiar: the money runs out before the month does. You get paid, bills get settled, a few “treat yourself” purchases sneak in, and by the third week you’re staring at your bank balance wondering where it all went. If this sounds like your life, you are far from alone. Millions of people, across every income bracket, struggle with the same invisible leak in their finances: uncontrolled expenses.
The good news is that this is one of the most solvable problems in personal finance. You don’t need a six-figure salary or a finance degree to keep your expenses under control. What you need is a system, a habit, and a monthly budget that actually reflects how you live. This guide walks you through exactly why expense control matters, why a monthly budget is the single most powerful tool for financial stability, and how to build one that you’ll actually stick to.
By the end of this article, you’ll have a clear, practical roadmap you can start using today, whether you’re trying to escape the paycheck-to-paycheck cycle, save for a big goal, get out of debt, or simply stop feeling anxious every time you check your bank account.
Why Controlling Expenses Matters More Than You Think
It’s tempting to believe that the solution to financial stress is simply earning more money. And while a higher income certainly helps, countless studies and real-world examples show that people who earn a lot can still live paycheck to paycheck, while people with modest incomes can build real wealth. The difference almost always comes down to one thing: how well they control their expenses.
Controlling your expenses isn’t about deprivation. It’s about direction. When you know exactly where your money is going, you gain the power to redirect it toward what actually matters to you, whether that’s an emergency fund, a dream vacation, your children’s education, or early retirement. Without that control, your money quietly drifts toward whatever demands your attention first: subscriptions you forgot about, impulse purchases, food delivery apps, and lifestyle upgrades that happen so gradually you barely notice them.
Here’s why expense control deserves your serious attention:
- It reduces financial stress. Studies consistently link money worries to anxiety, poor sleep, and strained relationships. Knowing your expenses are under control removes a massive mental burden.
- It builds real wealth over time. Every dollar you don’t waste is a dollar that can be saved, invested, or used to pay down debt faster.
- It gives you options. An emergency fund means a surprise car repair or medical bill doesn’t derail your entire month. Controlled expenses mean you can say yes to opportunities, like a career change or a big move, without panicking about money.
- It protects your future self. Small overspending habits today compound into missed retirement savings, ongoing debt, and financial dependence later in life.
- It improves your relationship with money. Instead of avoiding your bank statements out of fear, you start to feel confident and in control.
The Importance of a Monthly Budget
If controlling expenses is the goal, a monthly budget is the vehicle that gets you there. A budget is simply a plan for your money before you spend it, rather than a summary of where it went after the fact. This distinction matters enormously. Reactive spending, where you spend first and hope there’s enough left for savings, almost always leads to shortfalls. Proactive budgeting, where you decide in advance how every dollar will be used, flips the entire dynamic in your favor.
A Budget Gives You Visibility
You cannot control what you don’t measure. Most people underestimate how much they spend on categories like dining out, subscriptions, and small daily purchases. A monthly budget forces you to confront the real numbers, which is often the single biggest wake-up call in someone’s financial journey.
A Budget Prevents Lifestyle Creep
As income rises, spending tends to rise right along with it, a phenomenon known as lifestyle inflation. Without a budget, raises and bonuses quietly get absorbed into slightly nicer everyday spending instead of building your savings. A budget acts as a guardrail, ensuring that at least a portion of every extra dollar goes toward your long-term goals.
A Budget Reduces Decision Fatigue
When you haven’t planned your spending, every purchase becomes a small negotiation with yourself. A clear monthly budget removes this friction. You already know how much you have allocated for groceries, entertainment, or clothing, so decisions become quicker and less emotionally draining.
A Budget Turns Goals Into Numbers
“I want to save more” is a wish. “I will save 15,000 this month by cutting dining out to 3,000 and moving the difference into savings” is a plan. A monthly budget translates vague financial goals into specific, trackable actions, which dramatically increases the odds you’ll actually achieve them.
A Budget Prepares You for the Unexpected
Life is unpredictable, but your budget doesn’t have to fall apart because of it. A well-structured monthly budget includes a buffer for irregular expenses and a plan for building an emergency fund, so surprises become manageable instead of catastrophic.
How to Build a Monthly Budget That Actually Works
Creating a budget is simple in theory but often falls apart in practice because it’s built on guesswork instead of real numbers, or because it’s so restrictive that it becomes impossible to follow. Here’s a step-by-step approach designed to be realistic and sustainable.
Step 1: Track Your Real Spending for 30 Days
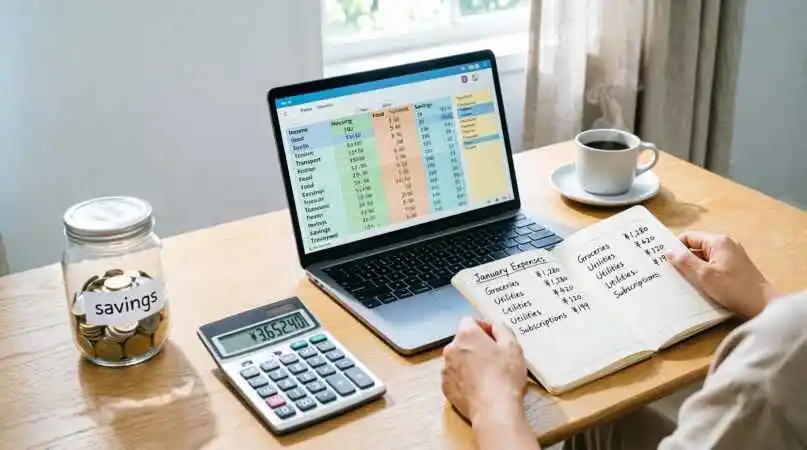
Before you build a budget, you need an honest picture of your current spending. For one full month, track every expense, no matter how small. Use a notebook, a spreadsheet, or a budgeting app, whichever you’re most likely to actually use consistently. At the end of the month, categorize everything into groups like housing, groceries, transportation, entertainment, subscriptions, and miscellaneous. Most people are genuinely surprised by at least one category, often discovering they spend far more on food delivery, coffee, or subscriptions than they assumed.
Step 2: Calculate Your True Monthly Income
Use your actual take-home income after taxes and mandatory deductions, not your gross salary. If your income varies month to month, calculate an average based on the last six to twelve months, and budget conservatively based on your lowest typical month.
Step 3: List and Categorize Every Expense
Separate your expenses into fixed costs, which stay the same each month such as rent, loan payments, and insurance, and variable costs, which fluctuate such as groceries, fuel, and entertainment. Don’t forget irregular expenses like annual subscriptions, festival spending, or insurance premiums; divide these by twelve and set aside that portion every month so they don’t catch you off guard.
Step 4: Choose a Budgeting Framework
Pick a structure that matches your personality and financial situation:
- The 50/30/20 rule: 50% needs, 30% wants, 20% savings and debt repayment. Great for beginners who want simplicity.
- Zero-based budgeting: Every unit of income is assigned a specific job until income minus expenses equals zero. Ideal for people who want maximum control.
- The envelope method: Cash is divided into physical or digital envelopes for each spending category. Excellent for people prone to overspending on cards.
- Pay-yourself-first budgeting: Savings and investments are deducted automatically before any other spending happens. Great for people focused on aggressive saving.
Step 5: Set Realistic Category Limits
Using your 30-day tracking data as a baseline, set spending limits for each category that are ambitious but achievable. If you currently spend 8,000 on dining out, dropping straight to 1,000 is unlikely to succeed. Instead, aim for a gradual reduction, such as 5,000 in the first month, tightening further as the habit sticks.
Step 6: Automate What You Can
Set up automatic transfers to your savings account on payday, before you have a chance to spend that money elsewhere. Automating fixed bill payments also reduces the risk of late fees and the mental load of remembering due dates.
Step 7: Track, Review, and Adjust Weekly
A budget is not a one-time document; it’s a living plan. Set aside fifteen minutes each week to check your spending against your budget. This weekly rhythm catches small overspending before it snowballs into a blown budget by month’s end, and it keeps your goals fresh in your mind.
Step 8: Do a Full Monthly Review
At the end of each month, compare your actual spending to your planned budget. Identify which categories went over and why, celebrate the categories where you stayed on track, and adjust next month’s numbers based on what you learned. Budgeting improves with iteration, not perfection.
Practical Strategies to Keep Your Expenses Under Control
A budget gives you the framework, but day-to-day habits are what actually keep your spending in check. Here are proven, practical strategies you can start applying immediately.
1. Use the 24-Hour Rule for Non-Essential Purchases
Before buying anything that isn’t a planned necessity, wait 24 hours. This simple pause interrupts impulse spending and gives your rational brain time to catch up with the initial excitement of a purchase. Many people find that the urge to buy fades entirely once the impulse has passed.
2. Audit and Cancel Unused Subscriptions
Subscriptions are one of the sneakiest budget killers because each one feels small on its own. Streaming services, apps, gym memberships, and software subscriptions can quietly add up to a significant monthly drain. Go through your last three bank statements and cancel anything you haven’t used in the past month.
3. Plan Meals and Shop With a List
Food is one of the largest and most controllable variable expenses. Planning meals in advance, shopping with a list, and avoiding grocery trips while hungry can meaningfully cut your monthly food bill without sacrificing quality of life.
4. Separate Needs From Wants Honestly
Before every purchase, ask whether it’s a genuine need or a want dressed up as a need. This isn’t about eliminating wants entirely, since a sustainable budget should include room for enjoyment, but about making that spending a conscious choice rather than an automatic reflex.
5. Use Cash or a Separate Card for Problem Categories
If a specific category, such as dining out or online shopping, consistently blows your budget, try using cash or a dedicated prepaid card loaded with only that month’s allotted amount. Once it’s gone, spending in that category stops for the month.
6. Negotiate Recurring Bills Annually
Insurance premiums, internet plans, and phone bills are often negotiable, especially if you’re willing to call and ask, compare competitor rates, or threaten to switch providers. A single phone call once a year can save a meaningful amount with almost no ongoing effort.
7. Avoid Lifestyle Inflation After a Raise
When you get a raise or bonus, resist the urge to immediately upgrade your lifestyle. Instead, direct at least half of any new income straight into savings or debt repayment before adjusting your everyday spending.
8. Build a Small Buffer Category
Rigid budgets tend to fail because life doesn’t move in straight lines. Build a small “miscellaneous” or buffer category into your budget for unplanned small expenses, so one unexpected cost doesn’t derail your entire plan.
9. Use the Envelope System for High-Risk Categories
For categories where you consistently overspend, allocate a fixed cash amount at the start of the month and physically separate it. This tactile limit is often far more effective than a number on a spreadsheet.
10. Automate Savings Before You See the Money
The most reliable way to save consistently is to remove the decision entirely. Set up an automatic transfer to a separate savings account the same day your paycheck arrives, so you’re budgeting with what’s left, not what’s left after you’ve already spent.
11. Set a Weekly Spending Cap, Not Just a Monthly One
Monthly budgets can feel abstract, especially early in the month when the full amount still looks generous. Breaking your variable spending categories, like groceries and entertainment, into a weekly cap makes the numbers feel more immediate and easier to track. It also means a single bad week doesn’t necessarily wreck your entire month, since you still have several weeks left to course-correct.
12. Review Your Bank and Card Statements Line by Line
It’s easy to glance at a total balance and assume everything is fine. Once a month, go through every single line item on your statements. This slow, deliberate review often reveals forgotten charges, duplicate subscriptions, or small merchant fees that would otherwise go unnoticed indefinitely.
Common Budgeting Mistakes That Sabotage Expense Control
Even well-intentioned budgets often fail, not because budgeting doesn’t work, but because of a handful of common, avoidable mistakes.
- Making the budget too restrictive: A budget with zero room for enjoyment is a budget people abandon within weeks.
- Forgetting irregular expenses: Annual insurance premiums or festival spending can blow apart an otherwise solid monthly budget if they’re not planned for in advance.
- Not tracking spending consistently: A budget without regular tracking is just a wish list; the tracking is what makes it real.
- Setting unrealistic category limits: Basing limits on what you think you should spend, rather than what you actually spend, sets you up for repeated failure.
- Giving up after one bad month: A single month of overspending doesn’t erase the value of budgeting; the goal is long-term consistency, not perfection.
- Ignoring small recurring charges: Subscriptions and small daily purchases feel insignificant individually but often represent a large chunk of monthly overspending.
Tools That Make Expense Control Easier
While a notebook and a calculator are enough to start, the right tools can make ongoing expense control significantly easier.
- Budgeting apps: Many apps can automatically categorize transactions, track spending against your budget, and send alerts when you’re approaching a limit.
- Spreadsheets: A simple monthly spreadsheet with income, fixed expenses, variable expenses, and savings gives you full customization and control.
- Automatic transfers: Most banks allow you to schedule recurring transfers to savings accounts, making “pay yourself first” effortless.
- Bill reminders: Calendar alerts or app notifications for due dates help you avoid late fees, which are an entirely avoidable expense.
Whichever tool you choose, the most important factor is consistency. The best budgeting system is the one you’ll actually use every week, not the one with the most features.
Building Long-Term Financial Discipline
https://youtu.be/iEjuL0nUrHg