Peloton’s internal crises occurred against a backdrop of an increasingly hostile external environment. The pandemic boom did not just enrich Peloton; it alerted every major tech and fitness company in the world to the viability of connected fitness.
As Peloton stumbles, its competitors are moving in for the kill.
Apple Fitness+: Apple represents the most existential threat to Peloton’s software pivot. Apple Fitness+ is deeply integrated into the Apple ecosystem (Apple Watch, iPhone, Apple TV). It costs $9.99 a month—cheaper than Peloton’s app tier—and offers a polished, highly produced suite of classes. While Apple lacks the cult-of-personality instructors that Peloton boasts, their sheer scale, hardware integration, and brand loyalty make them a formidable opponent.
Lululemon (Mirror): The athletic apparel giant bought the at-home mirror startup for $500 million during the pandemic. While Mirror has struggled with its own sales slumps, Lululemon has deep pockets and a massive retail footprint to push the product.
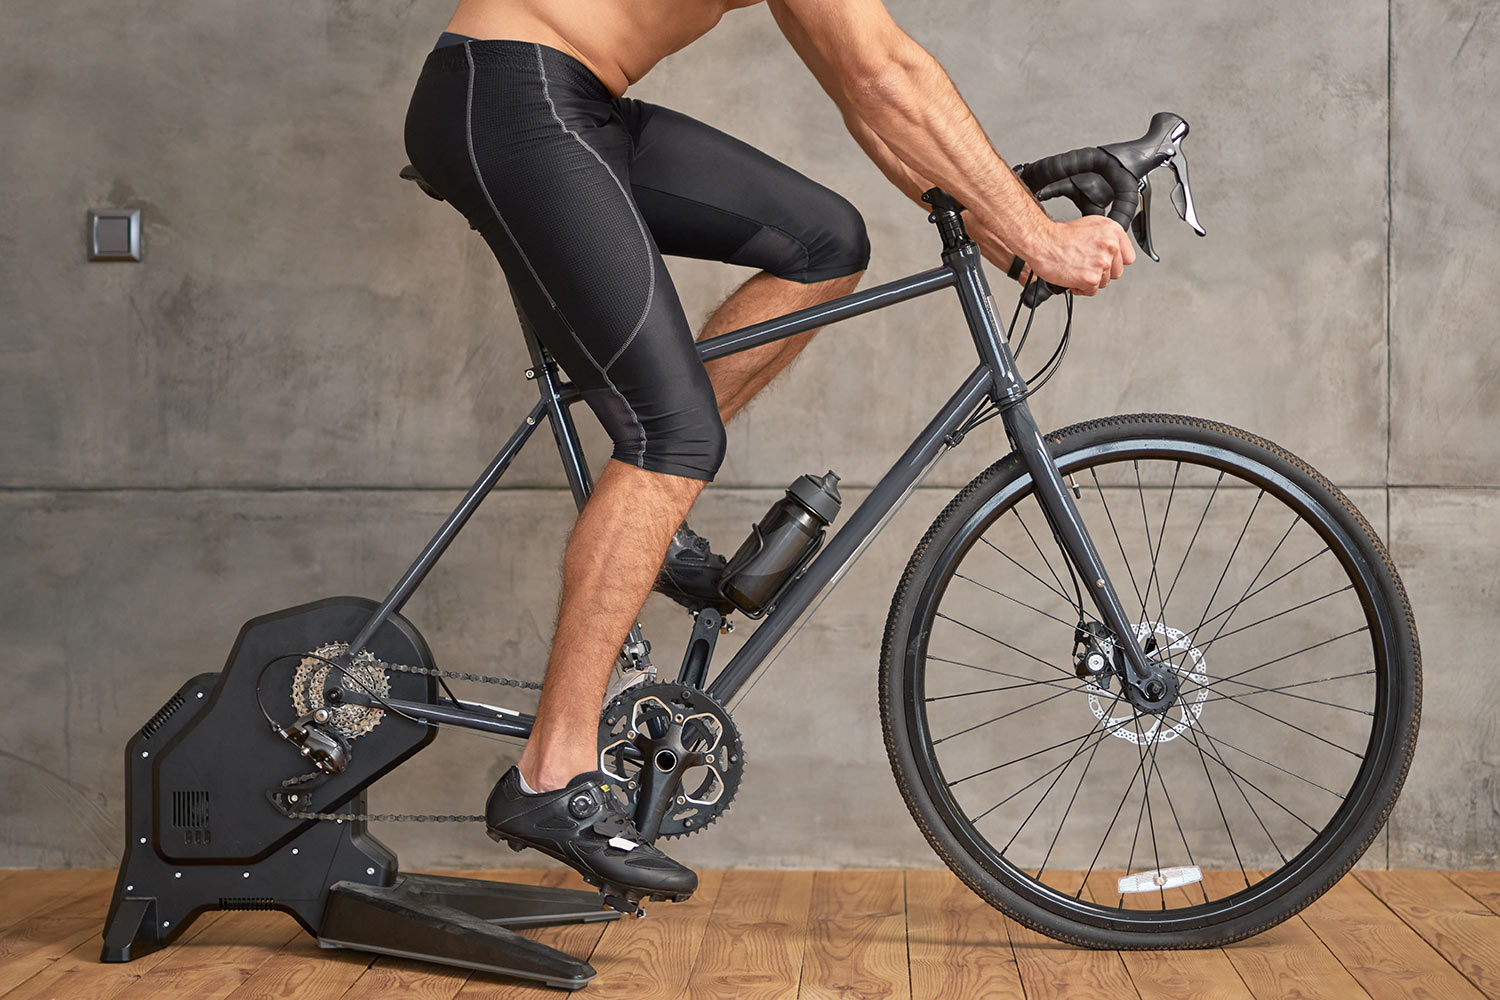
Echelon, iFit, and Bowflex: These companies were the “fast followers.” They produced cheaper, stripped-down versions of the Peloton Bike. During the pandemic, they couldn’t compete because demand was so high that consumers would pay a premium for a Peloton. Now, as consumers are price-sensitive, a $500 Echelon bike looks much more appealing than a $1,200 Peloton. Furthermore, iFit’s recent partnership with Google to integrate their software into smart TVs bypasses the need for expensive hardware entirely.
The Traditional Gyms: Planet Fitness reported record sign-ups in 2021 and 2022. The traditional gym model, which Foley famously predicted would die, is proving incredibly resilient. People crave the physical separation of home and gym, the variety of equipment, and the in-person social interaction that a screen in a living room simply cannot replicate.
Peloton is no longer the only game in town. It is a wounded animal in a forest full of predators. Barry McCarthy must not only fix the internal mechanics of the company; he must fight a multi-front war against competitors with deeper pockets and broader ecosystems.
Chapter 9: Can the Peloton Community Survive the Cuts?
The most pressing question for the long-term viability of Peloton is not about supply chains or app pricing; it is about the community.
The “One Peloton” community is the company’s only true, defensible moat. The rabid devotion of its user base—evidenced by the massive Facebook groups, the instructor fan clubs, and the high engagement metrics—is what justified its massive valuation in the first place. People didn’t just buy a bike; they bought into a lifestyle.
But communities are fragile. They are built on trust, shared experience, and a sense of mutual belonging.
How does a community survive when 2,800 of the people who built it are fired? How does the “family” ethos hold up when retail stores—the physical manifestation of that community—are shuttered and locked? How do instructors, who were treated like royalty, maintain their authenticity when they know their colleagues in the marketing and logistics departments have been unceremoniously let go?
There is a risk that the magic disappears. If the brand is perceived as just another struggling tech company cutting costs to appease Wall Street, the cool factor evaporates. And without the cool factor, a $40 a month subscription for spinning classes becomes a very tough sell in a inflationary economic environment where consumers are cutting discretionary spending.
McCarthy is aware of this. He knows that he cannot slash and burn his way to prosperity if he destroys the brand in the process. The delicate balancing act for the new CEO is preserving the soul of Peloton while amputating its bloated limbs.
Some early signs are positive. The instructors have, by and large, remained publicly supportive and continue to deliver high-energy classes. The core user base, those who use the bike daily, seem largely unbothered by the Wall Street drama; they care about the workout, not the stock price.
However, as the company scales back on live class offerings and pushes harder toward digital-only app users, the sense of intimacy and exclusivity that defined the early Peloton experience will inevitably dilute. The question is whether a diluted, mass-market Peloton can generate enough revenue to survive.
Conclusion: The Ride Goes On, But the Road Has Changed
The saga of Peloton is a quintessential 21st-century business tragedy. It is a story of a company that mistook a temporary, crisis-induced shift in consumer behavior for a permanent evolutionary leap. It is a tale of a charismatic founder who confused a rising stock price with operational genius, leading to a spectacular overextension of resources.
The decision to cut 2,800 jobs and replace John Foley with Barry McCarthy was not a surprise; it was an inevitability. The mathematics of the situation left the board with absolutely no other choice if they wished to avoid bankruptcy.
The layoffs represent a brutal, necessary correction. The era of Peloton building its own warehouses, staffing them with premium labor, and manufacturing its own hardware in the American Midwest is over. The era of spending millions on Super Bowl ads and quirky, tone-deaf holiday commercials is dead.
Peloton is now in the survival business. Barry McCarthy is attempting an incredibly difficult pivot—transitioning from a high-end hardware seller to a scalable software platform, all while fending off Apple, Lululemon, and a resurgent traditional gym industry.
Will he succeed? The odds are long. The connected fitness space is incredibly crowded, and the macroeconomic environment—with rising interest rates and shrinking consumer wallets—is hostile to premium discretionary purchases. Peloton may never see its stock price return to the stratospheric highs of $160. It may eventually be acquired by a larger tech or media conglomerate looking for its content library.
But the company is not dead yet. It still boasts millions of highly engaged subscribers. It still employs some of the best fitness instructors in the world. It still has a recognizable brand name that, despite the recent bruising, carries weight in the wellness space.
The Peloton of 2022 is a humbler, leaner, and perhaps wiser organization. The rose-colored glasses have been shattered. The pandemic mirage has dissipated. What remains is a fundamentally sound idea—high-quality, guided fitness in the home—now forced to prove its worth in the harsh, unforgiving light of reality.
The bike is still spinning. The instructors are still cueing the music. But for Peloton, the uphill climb has only just begun.
Disclaimer: The content on this blog is for informational purposes only. Author’s opinions are personal and not endorsed. Efforts are made to provide accurate information, but completeness, accuracy, or reliability are not guaranteed. Author is not liable for any loss or damage resulting from the use of this blog. It is recommended to use information on this blog at your own terms.