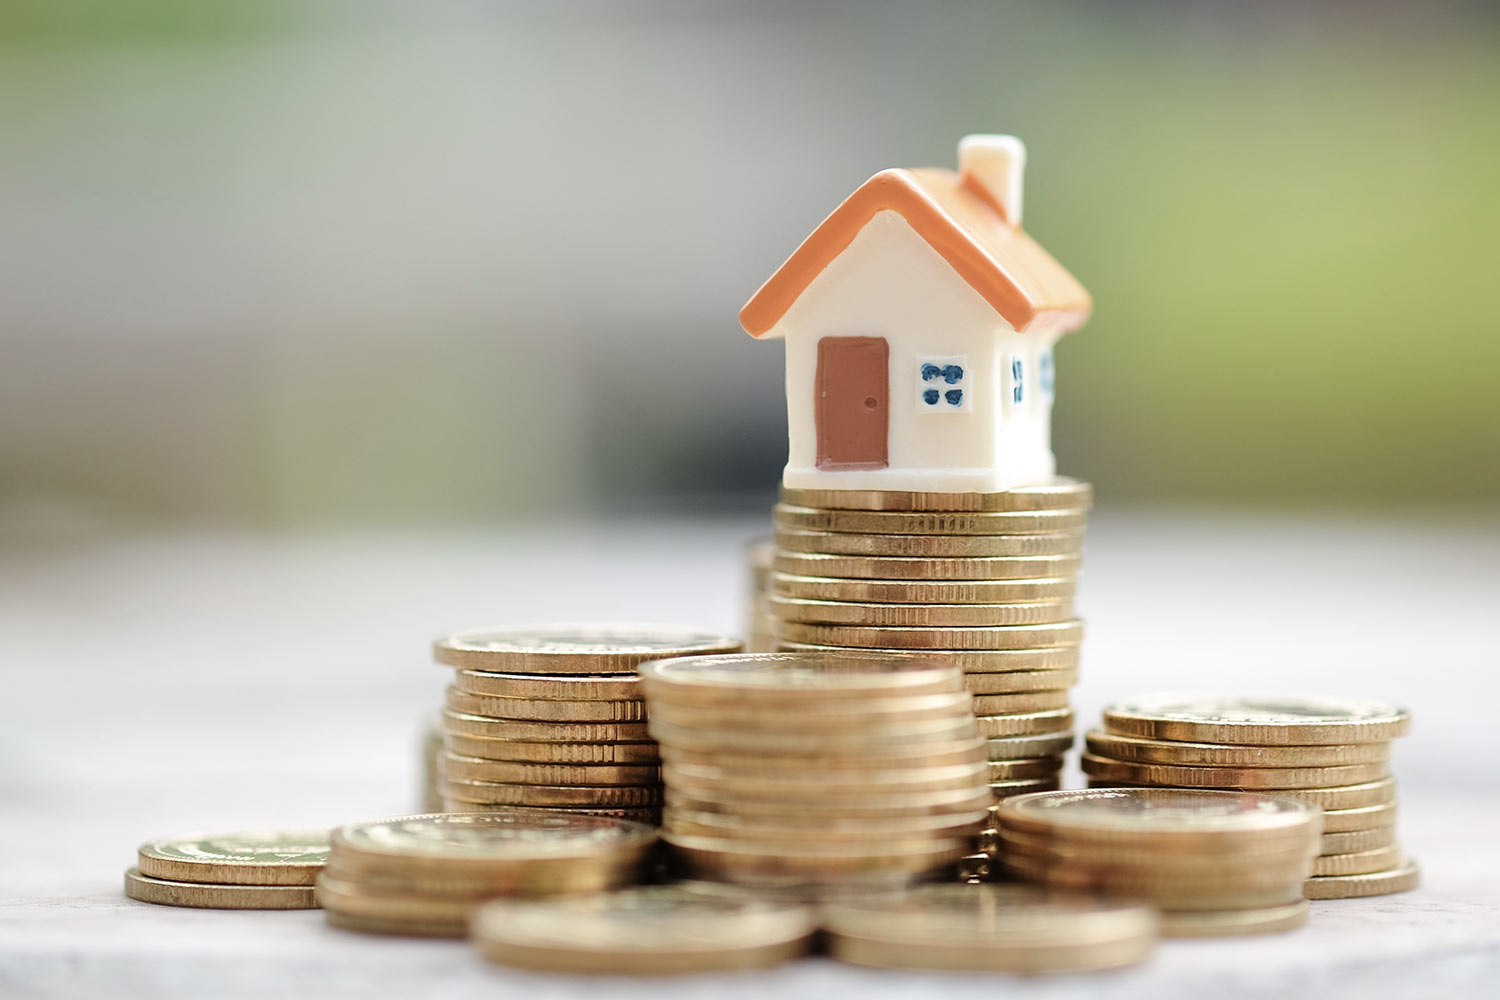
If organizing neighbors is the hardest emotional hurdle, financing is the hardest structural one. The mainstream banking system is explicitly designed to facilitate individual, profit-driven homeownership. It does not know what to do with four people who want to buy a building together as a non-profit collective.
We went to three high-street banks. The conversations were almost comically depressing.
Bank 1: “So, who is the actual borrower?” Us: “We all are. The cooperative is the borrower.” Bank 1: “We can’t lend to four people for one mortgage. One of you needs to be the legal owner.” Us: “But that defeats the entire purpose of a co-op. We don’t want an individual owner.” Bank 1: “I’m sorry, that’s not how our mortgages work.”
High-street banks look at co-ops and see risk. They can’t easily repossess a building if it’s owned by a cooperative entity; they would have to foreclose on a whole community. Furthermore, because we are a Limited-Equity Co-op, the value of the “asset” (from a capitalist perspective) won’t skyrocket over time. The bank can’t use our rising equity as a safety net.
We realized we had to step outside the mainstream financial system. We turned to Ethical Banks and Community Development Finance Institutions (CDFIs).
Organizations like Triodos Bank, the Ecology Building Society, and various community land trusts exist specifically to fund projects that traditional banks ignore. They understand the co-op model. They assess risk based on the financial stability of the group and the viability of the monthly charges, rather than just looking at individual salaries and property speculation.
However, ethical banks still require a substantial deposit. We needed to raise roughly 25% of the purchase price in cash.
This is where the true sacrifice came in. We emptied our savings accounts. The retired teacher in Flat 4 cashed in a small pension. We asked our families for loans (a deeply uncomfortable conversation, asking parents to risk their retirement savings on an experiment). We ran crowdfunding campaigns in our local community, framing it not as a charity handout, but as a “community investment” where people could lend us small amounts at low interest.
It was terrifying. For a few weeks, all our money was tied up in escrow accounts, and if the deal fell through, we risked losing it all. The financial system makes it incredibly dangerous for working-class people to attempt collective ownership. It requires a leap of faith that those with generational wealth never have to take.
The Bureaucratic Slog and the Emotional Rollercoaster
I want to pause the narrative of the process to talk about the psychological toll of trying to start a co-op.
When you buy a house, you hire a conveyancer, they do the paperwork, and you wait. When you start a co-op, you are the project managers.
For six months, my partner and I essentially took on a part-time, unpaid job. We were dealing with solicitors, negotiating with the landlord’s agent, fighting with mortgage brokers, running governance workshops with our neighbors, and trying to hold down our actual jobs at the same time.
There were nights when we sat at the kitchen table at midnight, staring at spreadsheets of projected maintenance costs, and one of us would break down.
“What are we doing?” my partner asked one night, tears of exhaustion in her eyes. “We could just rent another flat. Why are we putting ourselves through this?”
It’s a valid question. The answer is that by month four, the co-op stopped being just about our flat. It became a political act.
Every time we hit a bureaucratic wall—like the time the Land Registry refused to register our Cooperative Society because of a minor formatting error on a form, delaying the whole process by three weeks—the anger kept us going. The system is not broken; it is functioning exactly as intended. It is designed to exhaust you into accepting the default option: renting from a landlord or taking on a crushing, individualistic mortgage.
We also had to manage the emotional dynamics within our new cooperative. Flat 2 (the skeptics) had moments of panic and threatened to pull out, which would have collapsed our mortgage application. We had to learn conflict resolution. We had to learn to separate our personal relationships from our business relationships. We had to learn to govern ourselves.
Self-governance is exhausting. Democracy takes time. Deciding on something as simple as what color to paint the hallway becomes a committee meeting. But as tedious as it is, it is infinitely preferable to autocracy. I would rather spend three hours debating a hallway color with my neighbors than spend three seconds accepting a landlord’s dictate that we aren’t allowed to hang pictures on the walls.
The Alternative – What Life in a Co-op Actually Looks Like
As we neared the finish line of the legal and financial mazes, we began to vision what life would actually look like on the other side. How does a co-op function day-to-day?
Replacing Rent with “Carrying Charges”: Instead of paying rent to a landlord, we will pay a monthly “carrying charge” to our cooperative. This charge covers three things:
- The mortgage repayment (the cost of buying the building).
- A monthly contribution to the Reserve Fund (our savings account for future repairs, like a new roof).
- A small fee for building maintenance (paying a cleaner for the communal stairs, or an accountant for the co-op’s taxes).
Crucially, because we are a non-profit, our carrying charge is significantly lower than the market rent we were paying. Furthermore, when the mortgage is paid off in 25 years, the carrying charge drops to almost nothing, covering only maintenance and reserves. We will effectively live nearly rent-free in our retirement.
Democratic Control: Major decisions—like setting the carrying charge, approving a new member, or undertaking a massive renovation—are made at General Meetings. Every member gets one vote, regardless of the size of their flat. The retired teacher has the exact same voting power as the young professional couple.
Maintenance and Labor: Co-ops rely heavily on “sweat equity.” We don’t have a property manager to call when a lightbulb blows. We have a maintenance committee. If you are good at plumbing, you fix the pipes. If you are good at gardening, you tend the courtyard. It fosters a sense of ownership and pride that is completely absent in the rental market. You no longer view the building as someone else’s problem; it is your problem, in the best possible way.
Security and Stability: The most profound change will be the psychological shift. No one can evict us. No one can raise our rent to force us out so they can sell to a developer. If I lose my job, I know I won’t lose my home; the cooperative will work with me to figure out a payment plan.
The Finish Line (And the Realization That the Work is Just Beginning)
After eight agonizing months—eight months of paperwork, panic, meetings, and pooling every penny we had—we finally sat in a solicitor’s office and signed the final contracts.
I will never forget the moment the solicitor handed over the keys. Not to my landlord, not to an estate agent, but to us. To the four of us, acting as a single legal entity.
We walked back to our building. We opened the front door. It was the exact same door we had walked through a thousand times before. The scuff marks were still on the floor. The draft from the window was still there. But the feeling was entirely different.
The air felt lighter. The walls felt like they were actually ours. For the first time in my adult life, I was standing in a home that I could not be kicked out of. I was standing in a home that I had a democratic hand in governing. I was standing in a home that had been permanently removed from the speculative housing market.
But as we celebrated that night with our neighbors, drinking cheap wine in our slightly crooked kitchen, a sobering thought crept in.
Winning the co-op was just step one.
The housing crisis is not going to be solved by four people buying one building. The systemic forces that created the rental trap—financialization, lack of social housing, speculative investment—are still churning away outside our doors.
Our building is now an island of stability in a sea of precarity. But islands can be swallowed by the tide. If we want to protect our co-op, we have to help build more co-ops. We have to change the laws to make it easier for groups to incorporate. We have to push local governments to use empty public land for community land trusts. We have to fight for a world where housing is recognized as a human right, not a financial asset.
Our cooperative is no longer just our home; it is our organizing base. We are already talking to tenants in the buildings on our street. We are sharing our spreadsheets, our solicitor’s contact info, and our battle scars.
Conclusion: Breaking the Cycle
If you are reading this from a rented flat, staring at your own rising costs, and feeling the walls of the rental trap closing in, I want you to know that escaping it is possible. But it requires a fundamental shift in how you view housing.
You cannot beat the system by playing by its rules. You cannot out-earn a housing bubble. You cannot out-save corporate landlords who buy properties in cash. The only way out is to change the rules of the game entirely.
Turning our flat into a co-op was the hardest, most stressful, and most bureaucratic thing I have ever done. It required a level of trust in our neighbors that felt unnatural in our hyper-individualized society. It required us to risk our financial safety net on an experiment.
But I would do it again in a heartbeat.
Because the rental trap relies on isolation. It relies on tenants feeling powerless, atomized, and alone. The moment you knock on your neighbor’s door and say, “We can own this together,” the trap begins to shatter.
We didn’t just buy a flat. We built a tiny, four-person democracy. We took a piece of our city back from the speculators. We secured a permanent, affordable home for ourselves and for generations to come.
The rental trap is designed to keep you quiet, keep you moving, and keep you paying. Don’t just pay. Organize. Resist. Cooperate. Your home belongs to you.
Disclaimer: The content on this blog is for informational purposes only. Author’s opinions are personal and not endorsed. Efforts are made to provide accurate information, but completeness, accuracy, or reliability are not guaranteed. Author is not liable for any loss or damage resulting from the use of this blog. It is recommended to use information on this blog at your own terms.